
Traders are betting on a mild US winter

September 21, 2026

[This blog post is an excerpt from a commentary published last week at https://speculative-investor.com/]

The ‘super’ El Niño currently underway has contributed and will continue to contribute to extreme weather events or very unusual weather conditions, including reduced rainfall (and potentially severe drought) throughout Asia and an absence of Atlantic hurricanes. One of the likely future effects will be a relatively mild US winter. At least, that has been a result of a strong El Niño in the past. However, as discussed in a recent Bloomberg article, the greater the strength of the current El Niño, the greater the risk that historical weather and climate patterns will not be a reliable guide to the future.

The Bloomberg article linked above points out that traders have been betting for a few months now that a strong El Niño will deliver a mild US winter. Apart from the markets that facilitate direct betting on or hedging of future weather, this has been evident in the US natural gas (NG) futures market, where the total speculator net-short position is at its highest level since March-2020 and not far from a 20-year high.

Partly in response to speculation that the coming winter will be unusually mild, the January-2027 NG futures contract is at its lowest level in more than four years. Here’s a daily chart covering the past 12 months:
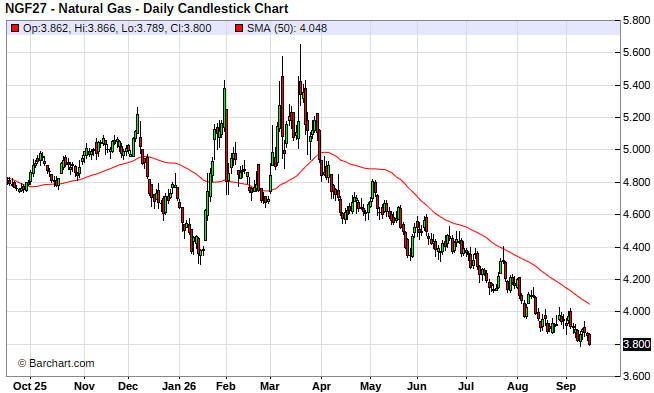
A relatively mild winter is the most likely outcome, but with this outcome already factored into current prices there is the potential for even an average winter to bring about a meaningful rally in the NG price. Also, the war in the Middle East has caused the price of NG in Europe to almost triple, resulting in Europe’s benchmark NG price now being almost 9-times the NG price in the US and creating an incentive to export as much Liquefied Natural Gas (LNG) as possible from the US. While this currently does not provide us with a set-up for a short-term NG trade with an attractive risk/reward, additional weakness or sideways movement in the price over the coming 1-2 months could generate such an opportunity.

The probability of a near-term Fed mistake

September 8, 2026

[This blog post is an excerpt from a recent commentary at https://speculative-investor.com/]

A Fed rate hike won’t enable more ships to go through the SOH or refineries to produce more diesel or farmers to grow more corn. In more general terms, when prices are rising due to supply restrictions, central-bank rate hikes are not a reasonable response. In fact, when the underlying problem is reduced supply due to temporary disruptions, a rate hike by the central bank is not only not part of the correct response but also gets in the way of the actions that are needed to fix the problem. What’s required is investment to increase production, not tighter monetary conditions to clamp down on demand. However, many commentators are arguing that the Fed should hike in September because “inflation is well above the Fed’s target!”.

Unfortunately, most members of the FOMC also fail to account for economic reality and instead react blindly to the high-profile “inflation” numbers and to employment reports that are inaccurate to the point of uselessness. Of course, Trump’s threats against the Fed do not help. That’s because to maintain the appearance of independence, if any members of the FOMC were leaning towards rate cuts (none of them are at the moment), the President’s threats likely would push them in the opposite direction.

So, the situation is that regardless of what caused the increased inflation numbers and what’s the best way to address the issue, the financial markets assume that any economic statistic will make a rate hike more likely if it hints at larger price increases or a stronger economy. Consequently, in response to the latest news, last week the probability assigned by the Fed Funds Futures market to a Fed rate hike at the FOMC meeting on 16th September went from 70% on Tuesday down to 50% on Thursday and back up to 59% on Friday. Gold was the market that was most sensitive to these probability swings.

In effect, at the end of last week the Fed Funds Futures market was assigning a probability of almost 60% to a Fed mistake in the form of a rate hike in mid-September. We will be surprised if this particular mistake is made, but if it is it could be the catalyst for deeper corrections in the gold, equity and currency markets, with the gold price and the SPX dropping and the Dollar Index rising.